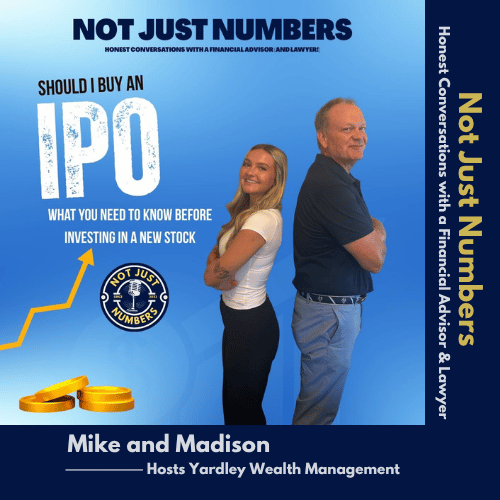
Episode 83: Should I Buy an IPO? What to Know Before Investing in a New Stock

Hosts: Madison Demora and Mike Garry

Episode Overview

Should you buy an IPO? When a well-known company goes public, it’s hard to avoid the headlines, and it’s tempting to wonder whether you should get in on it. In this episode of Not Just Numbers, Madison and Mike explain what actually happens when a company goes public, why most individual investors can’t buy at the offering price, and what lockup periods and the long-term data reveal. They also talk about why loving a company isn’t the same as owning a well-priced stock, and share the questions Mike walks clients through before they buy a hot new stock.

Listen to Our Podcast On:
TIMESTAMPS

00:08 – 03:12 – Introduction

03:13 – 05:09 – Why the Buzz Feels Like Information

05:10 – 08:04 – What Actually Happens When a Company Goes Public

08:05 – 10:36 – The Lockup Expiration and What Mature Really Means

10:37 – 12:22 – What the Long-Term Data Shows

12:23 – 19:52 – The Company You Believe In vs. the Price You’re Paying

19:53 – 21:11 – Closing

Follow Us on Social Media

Stay updated with the latest episodes and news by following us on social media:
 

Episode Glossary

  • Lockup Period: The time after the IPO when insiders, employees, and early investors are typically restricted from selling their shares for 90 to 180 days after the IPO.

Key Takeaways

  • IPO excitement is built on visibility, not value. When a company is everywhere in the news, it starts to feel like information, but a company getting attention and a stock being a good investment at the price available to you are two different things. Mike isn’t saying IPOs are always bad. Some are genuinely great businesses.
  • Most individual investors can’t buy at the offering price. After the roadshow and “book-building” with institutions, historically about 90% of IPO shares go to institutional investors. Since 1980, the average IPO has risen about 19% from its offering price to its first close, according to University of Florida research, and that jump goes mostly to the investors who got in first.
  • Lockup periods can add selling pressure. Insiders, employees, and early investors are typically restricted from selling for 90 to 180 days. When that ends, many more shares can hit the market at once.
  • Today’s IPO companies are more mature. The median company going public in 1980 had about $16 million in revenue (roughly $64 million in today’s dollars), compared with $218 million in 2024. Much of the growth now happens in private markets first, so you’re not necessarily getting in at the beginning.
  • The long-term data isn’t kind to IPO buyers. The University of Florida research found retail investors in IPOs underperformed comparable IPOs by roughly 20 percentage points in the first year. Of IPOs bought at the offer price, 56% were still down after three years and 57% after five. For those buying at the first-day close, about 60% were down after both.
  • A great company isn’t automatically a great stock. Believing in a company and having an investment case at a specific price are different things. Mike also noted that Peter Lynch’s “buy what you know” advice came with a second half: do the due diligence. Familiarity builds confidence, not investment discipline.
  • Before buying a hot new stock, ask: what percentage of my portfolio would this be, am I investing in the business or the narrative, what would have to be true for it to work long term, would I want to own it in 5 to 10 years, and what else could I do with the money? The goal is to slow the decision down before excitement takes over.

Transcript

Not Just Numbers: Honest Conversations with a Financial Advisor and Lawyer
Episode 83 – Should I Buy an IPO? What to Know Before Investing in a New Stock

Introduction & Hosts

Madison: Hello everyone and welcome to Not Just Numbers, Honest Conversations with a Financial Advisor and Lawyer, the official podcast of Yardley Wealth Management.

Mike: Official?

Madison: I am Madison.. Official, yes, yes we are.

Mike: Nice.

Madison: I am Madison Demora and I’m here with Mike Garry. Mike is a financial advisor and a CFP practitioner and the founder and the CEO of Yardley Wealth Management. He is also an estate planning lawyer and his law firm is Yardley Estate Planning. Hey Mike.

Mike: Hey Maddie, how are you?

Madison: I’m great. How are you?

Mike: I’m not too bad. Not too bad.

Why Everyone Wants In on an IPO

Madison: Awesome. So Mike, I want to start with something I think a lot of investors can relate to. A company announces that it’s going public, suddenly it’s everywhere in the news, everyone is talking about it, and people start wondering, “Should I get in on this?” Do you see that happen with clients?

Mike: Maddie, I have for my whole career. You know, I started in this business in 1998, and that was like towards the, you know, like the getting close to the frenzy of the dot-com era, and there were tech stocks going public all the time in in 98, 99, and the beginning of 2000, and it’s something like everybody wanted in on. You know, we’ll go into all the reasons for that later, but yeah, it’s something that’s always top of mind. There’s a company every year, there’s at least one company that attracts interest, and you know, I had a client email recently about whether you should get in on a big IPO everyone was talking about. And it’s a guy who never asked me about individual stocks, but this one felt different because it was everywhere. And that’s a pattern we see almost every time a recognizable name goes public. The questions that come in before the shares even begin trading.

Madison: So, why do you think that happens? Is it just fear of missing out or is it something… Or is there something more going on?

Mike: Yeah, so I think it’s both, right? I think there’s definitely some FOMO to it, but there’s more than that. So when something’s everywhere in the news, it starts to feel like information. And you start thinking like “Everyone else knows something I don’t.” But there’s a big difference between an IPO getting attention and an IPO actually being a good investment at the price available to you. And most of the excitement lives in that gap.

Madison: And that’s really what we want to unpack today. We’re going to talk about what actually happens when a company goes public, who gets access to the initial offering price, what happens after the opening-day excitement, what the longer-term data shows, and how investors can think through these opportunities before excitement turns into an investment decision. And Mike, I think it’s important to say up front: we’re not saying IPOs are automatically bad investments, right?

Mike: No, not at all. Some companies that go public are genuinely great businesses. The important distinction that this the story you’re hearing about a company and the price you’re being asked to pay for the company are two different things, and it helps to know the difference.

Why the Buzz Feels Like Information

Madison: Let’s start with the psychology behind all of this. Why does seeing a company everywhere suddenly make us feel like we should own it?

Mike: So there’s actually behavioral finance research around this. Investors tend to gravitate toward companies receiving a lot of media attention. And it’s not necessarily because the fundamentals suddenly make the company more attractive. Sometimes it’s simply because all that attention makes the decision feel easier.

Madison: So almost like our brains are saying, “If everyone’s talking about it, there must be something here.”

Mike: Exactly. It’s a mental shortcut. If a stock is everywhere, it feels like it must be worth looking at. But visibility and value are not the same thing. A company can dominate headlines for all kinds of reasons that have very little to do with whether it is priced well.

Madison: And there’s also a lot happening behind the scene when a company is preparing to go public, is that right?

Mike: That is absolutely correct. The marketing machinery behind an IPO is very, very real. You have roadshows, press coverage, executives doing interviews, and when they do an interview, they’re everywhere, right, for like five days, you you can’t avoid them. Analysts talking about the company. There’s an entire process designed to build awareness and momentum around the offering. It’s not necessarily criticism. It’s simply part of how the process works. It’s a big marketing machine.

What Actually Happens When a Company Goes Public

Madison: Here’s something I think might surprise people. When they’re seeing a lot of that coverage and thinking, “I want to buy at the IPO price,” are most individual investors actually able to do that?

Mike: Nope. And that’s one of the biggest disconnects. By the time the IPO becomes a major headline and individual investors are paying attention, the opportunity institutional investors had to buy shares at the offering price has largely already happened.

Madison: So the excitement we’re experiencing as individual investors and what’s actually happening behind the scenes are almost on two different timelines?

Mike: Exactly. And understanding those timelines is really important.

Madison: All right, so, let’s walk through the mechanics because I think this is where a lot of confusion comes from. What actually happens before a company rings the opening bell?

Mike: Before the company starts publicly trading, the investment bank handling the IPO typically runs what’s called a roadshow. Company executives present institutional investors, large asset managers, pension funds, and other major investors, and they gauge how much demand exists at different price points.

Madison: And that’s the process people here referred to as “book-building,” right?

Mike: Exactly. The investment bank is essentially building a book of demand and using that information to determine where the offering should be priced.

Madison: So by the time we hear it on the news, “This company priced its IPO at X dollars per share,” what’s already happened?

Mike: Right, a large percentage of those shares have already been allocated. Historically, like 90% of IPO shares have gone to institutional investors. So most individual investors aren’t buying at that offering price. They’re buying once trading opens.

Madison: And that could be a completely different price.

Mike: It can be. Since 1980, the average IPO has risen about 19% from the offering price to its first closing price across more than 9,000 deals, according to research from the University of Florida.

Madison: So if there’s a 19% jump, who actually captures that?

Mike: Yeah, well, the investors who are able to buy at the offering price. And again, that’s mostly institutional investors.

Madison: Which means the person sitting at home watching the stock open may already be paying significantly.

Mike: Yeah, significantly more. It’s worth understanding that some degree of underpricing is intentional, right? The underwriters want… Underwriters, which is like the banks that are taking them public, want enough demand for the shares, and a strong first day that can generate attention and enthusiasm around the offering, right? It’s all a big show, Maddie, and it’s to try to make the most for them and then for that company that’s going, you know, their customer that the company that’s going public.

Madison: But not every IPO shoots higher on day one.

Mike: No, definitely not. Some trade flat. Some decline. but those aren’t the ones getting the attention, right? The IPOs that tend to dominate the headlines are the ones making unusually large moves, up or down. So our perception of what a “normal IPO” looks like can become distorted by relatively small number of extreme examples. You know, it’s not every day that companies go public. But you know companies go public, more or less all the time, you know, like dozens a year at least go public. And we see the news around one or two of them, and it’s because like they rocket, or they’re like really disappointing. The ones they go up a little bit, eh, you don’t even hear about it.

Madison: So even before we get into investment performance, there can already be a perception problem.

Mike: Exactly.

The Lockup Period

Madison: Let’s move past opening day because there’s another part of this process that I don’t think many investors know about: the lockup period. What is that?

Mike: So a lockup period is the time after the IPO when insiders, employees, and early investors are typically restricted from selling their shares for 90 to 180 days after the IPO.

Madison: And what happens when that period ends?

Mike: Potentially, a lot more shares become available for sale. They want to get out. Employees and early investors who may have held those shares for years now have an opportunity to sell some of their holdings. And that increase in supply can create selling pressure around the lockup expiration. Right? If all of a sudden, you know, only 10% of shares are available at the IPO, and then 90 days later, the other 90% of people can sell, well, what’s going to happen? Some of those people are going to want to sell, and then all those shares flood the market, and people who were interested before are thinking about buying, and then the price can be distorted. It could be very, very different.

Madison: So the people who took the earliest risk in the company may be getting liquidity right around the time newer public investors are coming in.

Mike: That’s right. And leads into a bigger point about what it means when a company goes public today. The public often imagines they’re getting access to a young startup at the beginning of its growth story. That’s increasingly not the case.

What “Mature” Really Means

Madison: How different is it today compared with the past?

Mike: Yeah, so it’s a dramatic difference. In 1980, that probably sounds like dinosaurs were walking around 1982, right? I was still… I wasn’t in high school yet, but I was definitely around, the median IPO company going public had about 16 million dollars in revenue, adjust it for inflation, that’s like 64 million in today’s dollars. But the median in 2024 was $218 million. So like more than three times the size, you know, adjusted for inflation. So it’s a big difference.

Madison: Yeah, so a tremendous amount of growth has already happened before that company ever reaches the public market.

Mike: Yep. The growth from startup to a company generating hundreds of millions of dollars in revenue often happens in the private markets. Founders, employees, venture investors, and sometimes private equity partners participate in that earlier stage.

Madison: Does that mean investors should avoid companies just because they’re more mature when they go public?

Mike: No. Mature companies can still be fantastic investments. The point is simply that you’re entering at a different stage of the company’s life cycle than many investors realize. You’re not necessarily getting in at the beginning.

What the Long-Term Data Shows

Madison: All right, Mike, let’s talk about what happens after the headlines fade. What does the longer-term performance data tell us?

Mike: Well, that’s where things become much less exciting, Maddie. Research from again from the University of Florida found that retail investors who participate in IPOs underperform comparable IPOs by roughly 20 percentage points in the first year.

Madison: 20 percentage points in one year?

Mike: Yeah, that’s pretty significant, right? And when you look further out, the data doesn’t necessarily improve. 56% of IPOs bought at the offer price were still down after three years. And that number rises slightly to 57% after five years.

Madison: And that’s for people who actually got the offer price. What happens if you bought after the stock started publicly trading?

Mike: Exactly what you’re thinking. The numbers are even worse. For investors buying at the first day’s closing price, so after initial opening-day movement, about 60% of those IPOs were down after both three and five years.

Madison: So the person who’s most likely to see a headline, get excited and buy after the stock has already jumped may actually be starting from the least favorable position.

Mike: Yep, that’s the concern. By the time the excitement is obvious, some of that optimism may already be reflected in the price, maybe too much of it.

Madison: And I imagine that’s where the emotional side of investing becomes dangerous. You can have a company everyone loves and a stock that still doesn’t perform the way people expect.

Mike: The company, yeah, the companies that generate the most attention and enthusiasm aren’t automatically the ones that produce the best investment outcomes. Hype and investment performance can move in completely different directions.

The Company You Believe In vs. the Price You’re Paying

Madison: I think this might be the most important distinction in the whole conversation. Can someone be completely right about a company being innovative, successful, and potentially transformational, and still be wrong about buying the stock?

Mike: Yeah, absolutely. I mean, this is something that that you know we talk about a lot here, right? So, you know, people misunderstand Jeremy Siegel’s main tenet of Stocks for the Long Run, where he says that you buy stocks as an asset class, and over time they’ve outperformed adjusted for inflation other things you can invest in. And have had pretty consistent results for like 200 years. He’s not saying you buy any stock at any price and it will be a good investment. And people, for some reason, can’t stop conflating those two things. They think that, “Oh, I’m going to buy a stock and hold on, it’s going to be a good investment,” and no, it doesn’t have to be. You know, a company can be innovative, well-run and changing its industry and still be priced in a way that leaves very little upside for the new investor. You know, I think some of the MAGA stocks are like that now. Like, you know, like Nvidia has gone, you know, so much in the last you know number of years, you know, there’s not enough dollars on earth for it to continue growing at that extreme thing. So, you know, that that’s why believing in a company and having an investment thesis at a specific price are two different things. I can’t state that enough. So I’ll stop.

Madison: Yes, thank you, Mike. So when people say “I love this company. I use their products all the time. I think they’re going to be huge,” what are they potentially missing?

Mike: So this is this is the Peter Lynch misunderstanding, right? So Peter Lynch was the Fidelity Magellan fund manager from 1977 to 1990, outperformed the S&P 500 like 13 years in a row, had this great track record. And then he wrote books and he told people to like invest in what they know, buy what they know. And so you know people say, “Oh I really like this hair dryer, so I’m going to buy this hair dryer stock.” And it doesn’t work like that. You know he also said, you know, buy what you know, but then like do the due diligence on the stock being a good investment. People forget the second part of that. Right, like “Oh I love Pepsi, so I’m going to buy Pepsi,” well, you know, it’s missing the whole valuation, right? So like at an IPO, a lot of future growth may already be reflected in the price. So if you buy after a significant opening-day jump, you’re not simply betting that the company succeeds. You’re effectively betting that it performs even better than what the market already expects, and there are already high expectations. You know, I should say here that the fund companies that we use primarily, Avantis and Dimensional, don’t buy stocks when they come out. Like they wait for a company to be public, for at least a year, before they are included in their screens, because it’s historically just not been a good investment.

Familiarity Can Feel Like Confidence

Madison: And there’s a behavioral bias tied to that too.

Mike: Yep. Familiarity. So people are often feel more comfortable investing in companies they know personally. Maybe they use the product every day. Maybe they love the brand. Maybe they followed the company for years. You know, again, going back to Peter Lynch, so he had that great stock performance, it was also a time when retail stocks did best, right? And so it was like Nike and Adidas and like companies that like you knew familiar brands. Well, the next decade, you know, after he retired was the 90s, there was a lot of computer equipment, right? So Cisco was one of the best performing stocks. People didn’t know what a router even looked like, right? So like, you know, so maybe his timing was good. But that familiarity can create confidence, but confidence isn’t necessarily the same thing as investment discipline or a good investment approach.

Madison: I can imagine someone thinking, “I love this company, so of course I want to own a piece of it.”

Mike: Yeah, and then I don’t know if you remember this, but people used to buy a share of Disney stock and they stick it like in a frame, and like it’s cool that they own part of it. Well, it’s a cool thing, and maybe it’s a neat thing to put in the kids’ room. You know, it’s understandable. We see clients do it, you know, but loving the brand isn’t the same as determining whether the stock fits your portfolio or whether you’re getting it at an attractive price. Yeah, buy it because it’s cool, it’s like buying a painting to put in your kids room. Don’t buy a thousand shares because you like to go there every year, you know, unless you look into it and determine that it really fits in with your investments.

Questions to Ask Before Buying an IPO

Madison: So let’s say someone comes to you and says, “Mike, I really want to buy this IPO.” What questions would you walk them through?

Mike: Sure. The first question is like, what percentage of this of your portfolio would this represent? You know, are you thinking about buying a half percent, or do you want to go all in? Because yeah, all in is not a good idea. And then are we sizing this position based on a thoughtful investment strategy, or is it based on enthusiasm?

Madison: So even if they want to participate, position size matters.

Mike: Absolutely. You know, then I’d ask, are you investing in the business or are you investing in the narrative? A great story is not the same thing as a great business model. So, when I started at Merrill in the 90s, the narrative was like this big thing, you know, because it was a lot more of investing individual stocks, and so somebody could talk about like a story, like the narrative story of a stock, or like the theme of certain kinds of investments, and you know it could be really persuasive. It would make people want to buy the stock or like the theme of the fund. It’s not necessarily like a great business model. You know just because something has a good story doesn’t mean that it’s a good thing.

Madison: And what else do you walk them through?

Mike: Well, what would have to be true for this investment to work over the long term? Does the company simply need to execute well? Or does everything have to go perfectly for the valuation to make sense?

Madison: That’s an interesting way to frame it because it forces you to think beyond opening day.

Mike: Exactly. Another question is, would you still want to own this company five or 10 years from now? You know, Warren Buffett has made the point that if you’re not willing to own a stock for 10 years, you shouldn’t think about owning it for 10 minutes.

Madison: And I imagine there’s one more question that ties all of this back to somebody’s actual financial plan. What’s the alternative?

Mike: Right. What else could you be doing with that money? How does this opportunity compare with the other investments available to you? And, most importantly, how does it fit into your overall financial strategy?

Madison: So these questions aren’t meant to create a rigid checklist where the answer is always “don’t buy the IPO.”

Mike: No, not at all. It’s maybe mostly don’t buy the IPO, but they’re meant to slow down the decision, right? Like working through these questions before acting on excitement can completely change how you think about the opportunity and make it a well-informed decision, not just like, “Oh, I love this story, let’s go buy this.”

Staying Disciplined When the Excitement Is Loudest

Madison: So following a company you’re curious about is completely reasonable. Reading about what it does, watching how leadership handles being public, staying informed, that’s all fine.

Mike: Taking a position based on media coverage and opening-day momentum is a different decision, with real consequences. That is really where we can add the most value. Helping clients separate what the market is saying today from what their actual long-term strategy requires. We can help clients stay disciplined when the excitement is loudest, and help them see the difference between a compelling story and a well-priced investment.

Closing & Contact Information

Madison: And this is not about missing out on opportunities. It’s about making sure that the ones you act on are actually the ones that matter for your outcome.

Mike: If you have questions about your approach to IPOs, or whether a new opportunity fits into your overall financial strategy, we are here and happy to walk it through with you.

Madison: Awesome. Thanks, everyone.

Mike: Thank you, Maddie. This is great.

Madison: For more information on Yardley Wealth Management or Yardley Estate Planning, you could visit our websites at yardleywealth.net and yardleyestate.net. You can also follow us on socials at Yardley Wealth Management. Don’t forget to subscribe to our YouTube channel. This podcast has been produced by Madison Demora and Mike Garry with technical and artistic help from Poe Productions.

Request the Full Transcript as a PDF

The full transcript of this episode is available via email. Please fill out the form below to receive it: